Military & VA Home Buying
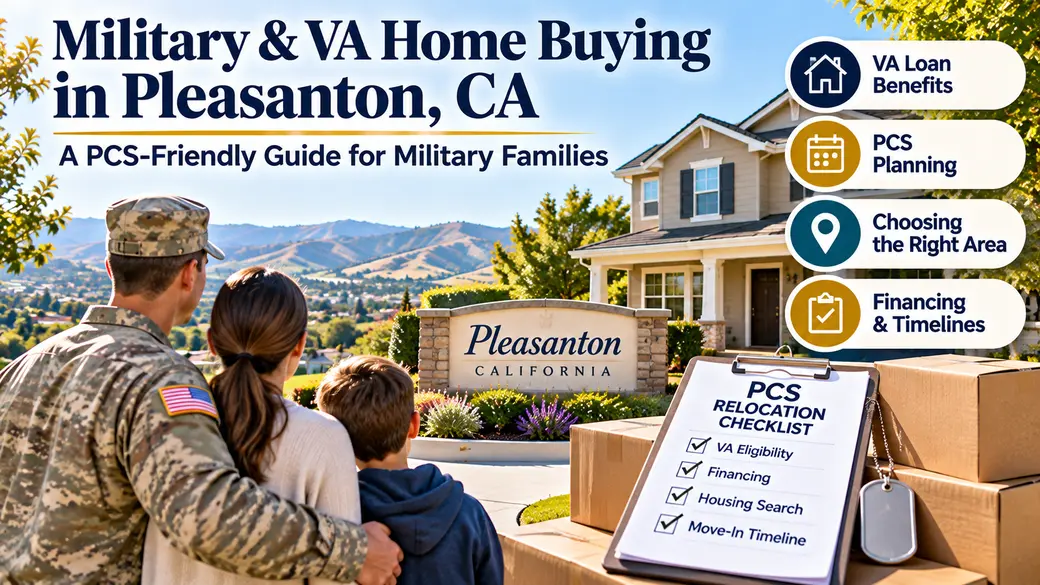
Military & VA home buying in Pleasanton, CA works best with an adaptable plan for PCS orders, deployments, and changing tour lengths. Confirm loan eligibility, set a realistic decision timeline, and decide whether buying before arrival supports your household's needs. This guide is for veterans, active-duty buyers, and military families weighing a Pleasanton purchase during a move.
How VA Home Loans Support Military & VA Home Buying
A VA-backed loan can help eligible borrowers with full entitlement buy a primary residence with no down payment and no private mortgage insurance. Start by requesting a Certificate of Eligibility, commonly called a COE, because it documents service-based eligibility and available entitlement for the lender.
The VA funding fee may apply, although some Veterans, service members, and eligible surviving spouses may be exempt. Funding-fee rules, entitlement details, and lender requirements can change, so confirm current guidance through the U.S. Department of Veterans Affairs before making an offer.
VA financing is designed for a home you intend to occupy as a primary residence. If PCS orders or deployment timing affects your move-in date, discuss the expected occupancy schedule and supporting documentation with your lender early. Addressing that timing before an offer can prevent avoidable complications as the loan file moves toward closing.
Planning Military & VA Home Buying Around PCS Orders
Military & VA home buying around PCS orders is easier when financing documents, decision-makers, and location priorities are organized as soon as a move becomes likely. A short timeline does not remove the need to evaluate payment comfort, commute routines, or a home's practical fit. It makes early coordination more important.
Buying before arrival can reduce temporary housing time and allow a household to move directly into a permanent home. Waiting until arrival can provide more opportunity to experience streets, traffic patterns, and daily routines firsthand.
| Option | Advantages | Limitations | Often fits buyers who |
|---|---|---|---|
| Buy before arrival | May reduce temporary-housing time and simplify the move | Requires confident remote decision-making | Have clear priorities, organized financing, and reliable local support |
| Buy after arrival | Allows in-person tours and commute testing | May require interim housing and a tighter closing calendar | Have time to explore Pleasanton before committing |
Remote video tours, detailed disclosures, and clear communication can make an early purchase workable. Before choosing either approach, decide who can review documents, respond to time-sensitive requests, and participate in decisions if travel or deployment affects availability. A clear authorization and communication plan is especially useful when one household member may be unavailable during the offer or closing period.
Choosing a Pleasanton Location Near Your Duty Station
The right Pleasanton location is one that makes the commute and your household's routine manageable. Test likely travel routes at the times you expect to drive, then consider how traffic, parking, school schedules, childcare, errands, and medical appointments shape a typical week.
Treat Main Street, Dublin/Pleasanton BART, and West Dublin/Pleasanton BART as separate destination tests. A home that works well for one destination may require a different trip to another, particularly when work schedules change or household members travel independently.
Neighborhood fit should extend beyond one amenity or a map distance. Compare usable living space, parking, lot layout, noise patterns, nearby services, and whether the home can support your household if work schedules or family needs change. The Pleasanton postal-city area has a median home value of $1,769,539, so buyers should review the full ownership picture, including financing, taxes, insurance, utilities, maintenance, and reserves, rather than focusing on price alone (Pleasanton, CA).
For military households, daily usability can matter more than a feature list. A different location or layout may be worthwhile if it makes storage, parking, commuting, and family routines easier to manage.
First-Time Buyer Essentials for VA Buyers
First-time VA buyers should build a budget around dependable income, including Basic Allowance for Housing when applicable, while leaving room for costs beyond the mortgage payment. Property taxes, insurance, utilities, maintenance, moving expenses, and cash reserves can all affect the comfort of ownership after closing.
Preapproval gives you a lender-reviewed borrowing range before you focus on specific homes. It is not final approval, which can still depend on the property, documentation, loan underwriting, and changes to your financial profile. Ask the lender how orders, allowances, debt, or employment timing could affect the file.
Earnest money is generally submitted after an offer is accepted and handled through escrow under the purchase agreement. Closing costs can include lender charges, title services, prepaid items, and transaction-specific expenses. VA rules limit certain charges to buyers, but the final amount depends on the loan structure and negotiated contract terms.
Use a lender-prepared payment estimate to test the expected payment, reserves, and closing funds. The goal is not simply to qualify for a purchase, but to select a payment level that remains workable through relocation costs, changing household needs, and future assignment decisions.
Buying on a Short PCS Timeline
A short PCS timeline can support a remote purchase when communication, documentation, and decision authority are established early. Live video showings allow buyers to ask questions in real time, compare layouts, request closer views of visible finishes, and examine areas that listing photos may not fully show.
Virtual tours are most useful when paired with property disclosures, focused follow-up questions, and attention to the home's immediate surroundings. Ask for views from each major room, storage areas, parking access, outdoor spaces, and the street approach, rather than relying only on an edited tour.
Remote closing may be possible depending on lender, title, and transaction requirements. Confirm identification procedures, notarization needs, wire instructions, and document-delivery expectations well before the closing window becomes urgent. Also establish who can receive updates and make prompt decisions if travel or deployment interrupts communication.
Buy or Rent After a PCS?
Buying after a PCS is often more practical when your expected assignment length, financial reserves, and household plans support ownership beyond the initial move. Renting can be the better choice when flexibility is more valuable than settling immediately into a long-term property.
| More suited to buying | More suited to renting |
|---|---|
| You expect to remain long enough to support ownership costs | Your next move may come quickly or your timeline is uncertain |
| You have funds for closing, reserves, and ongoing upkeep | You want to limit responsibility for maintenance and vacancies |
| The home could fit future household or rental plans | You need time to learn Pleasanton before choosing a location |
Future rental potential can be part of a longer-term strategy, but it should not be assumed. Consider carrying costs during a vacancy, management responsibilities from another location, lease restrictions where applicable, and how keeping the property could affect later VA entitlement decisions.
The VA Appraisal and Home Inspection Have Different Roles
A VA appraisal is not a home inspection because each serves a different purpose in a purchase. The appraisal helps the lender assess value and determine whether the home meets VA minimum property requirements. It does not provide a comprehensive, buyer-focused review of visible condition or future maintenance needs.
A home inspection is a separate review arranged for the buyer's benefit. It can identify visible concerns involving major systems, maintenance items, and repair priorities before you take ownership. The VA explains that an appraisal is not a home inspection and encourages buyers to understand the distinction.
Military buyers working from another location should arrange the inspection promptly after an accepted offer. A detailed written report, photos, video when available, and a conversation with the inspector can help remote buyers understand the findings and make informed decisions within the contract timeline.
Planning for Your Next Military Move
Military & VA home buying should account for the next move as well as the current assignment. After a future PCS, an owner may sell, retain the home as a rental, or seek entitlement restoration after a sale or payoff. Review those possibilities before buying so the home supports both present housing needs and a future transition.
Planning for future PCS orders is just as important as preparing for your current home purchase. If another assignment requires you to sell, understanding your home's value, available equity, selling timeline, and relocation deadlines can help you make informed decisions. For additional guidance, explore our home-selling considerations for military families navigating PCS moves in San Mateo to see how early preparation can support a smoother transition.
Michael Fadeeff of Serhant California, inc. helps military households coordinate Pleasanton home searches, remote tours, and closing timelines around PCS-related logistics.
Military families and veterans can work with Michael Fadeeff of Serhant California, inc. to plan Pleasanton home searches, VA loan offers, remote tours, and closings around PCS orders. Call [Phone] or email [Email] to begin planning your purchase.
FAQ
Is Pleasanton a good place to live?
Pleasanton can suit buyers looking for an established East Bay community, household-oriented amenities, and access to regional employment centers. The best fit depends on your commute, budget, preferred home layout, and expected length of stay. The Pleasanton postal-city area has an overall crime risk index of 50, compared with a U.S. average of 100, though that index should be considered alongside your own location, commute, and lifestyle priorities (Pleasanton, CA).
Is Pleasanton expensive?
Yes, Pleasanton is generally a higher-cost market for homeownership. Its cost-of-living index is 140, with housing at 132, where 100 represents the U.S. national average, so buyers should evaluate financing, taxes, insurance, utilities, maintenance, and reserves together.
What salary do you need in Pleasanton?
The salary needed to buy in Pleasanton depends on the home price, interest rate, debt obligations, down payment, available VA entitlement, and reserves. The area's median household income is $174,432, but a lender should assess your individual income, allowances, liabilities, and proposed payment rather than relying on an area benchmark alone.
Can I use my VA loan more than once?
Yes, eligible borrowers can use VA loan benefits more than once when entitlement requirements are met. Full entitlement is commonly restored after a prior VA-backed loan is paid off and the property is sold, while some borrowers may retain enough entitlement for another purchase.
Do I need a down payment with a VA loan?
Eligible borrowers with full entitlement may be able to purchase with no down payment. Lender requirements, purchase price, remaining entitlement, and the overall loan profile can affect the final loan structure.
Can I buy a home before I arrive at my new duty station?
Yes, you can buy before arriving by using remote tours, detailed property materials, and organized communication with local support. The process is strongest when financing documents, decision deadlines, and signing logistics are prepared early.
Does a VA loan require a home inspection?
No, VA financing does not require a home inspection. An inspection is still strongly recommended because it offers a separate review of visible condition and maintenance concerns, while the VA appraisal has a lender-focused role.
Categories
Recent Posts
GET MORE INFORMATION