Pleasanton Starter Home: What Buyers in 2026 Expect
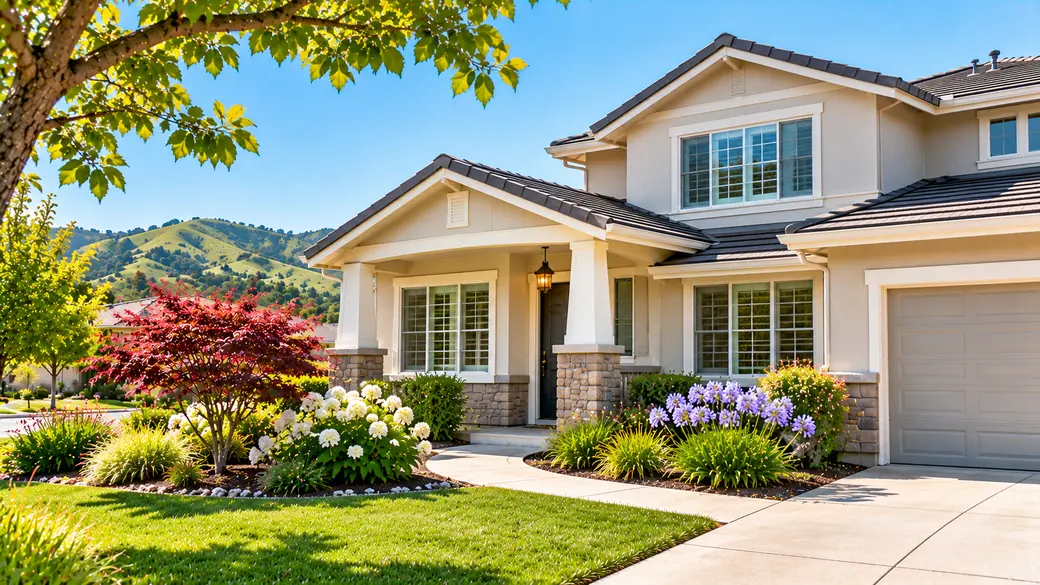
A Pleasanton starter home search in 2026 requires a payment-first strategy, flexible property expectations, and financing preparation before touring. The Pleasanton postal-city area has a median home value of $1,769,539, a useful benchmark for understanding why many entry-level buyers begin with condos, townhomes, smaller detached homes, or properties needing updates rather than expecting a turnkey detached house as the default (Pleasanton, CA).
Pleasanton Starter Home Market Snapshot - 2026
For a Pleasanton starter-home search, financing costs and the complete monthly payment are useful planning benchmarks.
- Mortgage rate: The average 30-year fixed mortgage rate was 7.18% on November 5, 2026, according to Freddie Mac’s Primary Mortgage Market Survey.
- Overall local value benchmark: Pleasanton’s postal-city median home value is $1,769,539.
- Ownership context: Owner-occupied homes account for 66.43% of occupied housing in the Pleasanton postal-city area.
- Buyer focus: Condos, townhomes, compact detached homes, and homes needing cosmetic updates are often the practical starting points for payment-conscious buyers.
What Counts as a Starter Home in Pleasanton Right Now
A Pleasanton starter home is the most attainable property that meets a buyer’s essential location, layout, and payment requirements, rather than a single standard home type. With a $1,769,539 overall median home-value benchmark, buyers commonly evaluate condos, townhomes, smaller detached homes, and homes where condition creates a lower initial purchase price.
In practical terms, a buyer may need to choose among more space, a renovated interior, a lower monthly payment, or a preferred location. Condos and townhomes can create a more accessible purchase threshold than many detached homes, although monthly HOA dues need to be included in the ownership budget. Smaller detached homes may appeal to buyers who value private outdoor space, but maintenance needs and renovation planning can become part of the tradeoff.
The starter-home definition has shifted because mortgage rates make the total monthly payment as consequential as the list price. Buyers who once expected a move-in-ready detached home may find that a condo, townhome, or home needing cosmetic work offers a more sustainable first ownership step.
A focused search begins with nonnegotiables such as commute needs, bedroom count, parking, accessibility, and recurring costs. The Pleasanton neighborhood overview can help buyers frame those tradeoffs around local housing context.
What Pleasanton Starter-Home Buyers Are Up Against in 2026
-
Payment sensitivity: A 7.18% average 30-year fixed rate can materially change a buyer’s monthly principal-and-interest payment, even with a meaningful down payment (Freddie Mac Primary Mortgage Market Survey, November 5, 2026).
-
Limited entry paths: Buyers seeking the lowest attainable purchase price often concentrate on condos, townhomes, smaller detached homes, and homes that need updates.
-
Move-up competition: Buyers with equity from an existing home can compete for well-located lower-priced properties when the layout, location, or renovation potential is compelling.
-
Income-to-price gap: Pleasanton’s overall housing-value benchmark creates a significant affordability hurdle, so buyers benefit from setting their ceiling according to the full monthly payment.
-
Condition tradeoffs: A lower list price can reflect deferred maintenance, HOA obligations, location compromises, or a layout that requires a longer-term ownership plan.
How Much Starter-Home Buyers in Pleasanton Need to Earn
Pleasanton starter-home buyers need income that supports the complete monthly housing payment, not only principal and interest. The following planning example uses the $1,769,539 Pleasanton postal-city median home-value benchmark as a high-level illustration, not as a starter-home quote.
Using a 7.18% 30-year fixed rate, a 3% down payment equals approximately $53,086:
- $1,769,539 × 3% = approximately $53,086 down.
- $1,769,539 − $53,086 = approximately $1,716,453 financed.
- Principal and interest on that loan at 7.18% for 30 years is roughly $11,650 per month.
- A 1% base property-tax estimate adds about $1,475 monthly before insurance, HOA dues, and voter-approved local charges.
At 10% down, the down payment would be about $176,954 and the loan amount about $1,592,585. Principal and interest would be roughly $10,810 per month, before taxes, insurance, HOA dues, and maintenance planning.
Using a 28% housing-payment guideline, the 3% down example would require roughly $563,000 in annual gross household income before allowing for insurance or HOA dues. The 10% down example would require roughly $526,000 annually on the same basis. That is substantially above Pleasanton’s $174,432 median annual household income. California’s base property-tax rate is 1% of taxable assessed value, before applicable voter-approved charges (California State Board of Equalization, accessed November 2026).
Starter Home Loan Options: Side-by-Side Comparison
FHA, conventional low-down-payment financing, USDA financing, and CalHFA assistance can serve different buyer profiles. Confirm program terms, income limits, property eligibility, and lender overlays before writing an offer.
| Loan program | Minimum down payment | Minimum credit score | Mortgage insurance rules | Income limit | Best-fit buyer profile |
|---|---|---|---|---|---|
| FHA | 3.5% | Lender underwriting applies | Upfront and annual mortgage insurance generally apply | No program-wide income limit | Buyer seeking a lower down payment and flexible underwriting |
| Conventional 97 | 3% | Lender and program eligibility apply | Private mortgage insurance is generally required above 80% loan-to-value | Depends on program type | Buyer with qualifying conventional financing and limited upfront cash |
| USDA | 0% for eligible borrowers and properties | No national minimum score requirement | Guarantee fees may apply | Cannot exceed 115% of area median household income | Buyer purchasing a primary residence in an eligible rural area |
| CalHFA MyHome assistance | Up to 3% with a CalHFA conventional loan, or up to 3.5% with a CalHFA FHA loan | Lender and paired first-mortgage standards apply | Depends on the paired first mortgage | CalHFA income limits apply | Eligible first-time buyer needing down-payment or closing-cost assistance |
Hidden Costs First-Time Buyers in Pleasanton Often Miss
Pleasanton first-time buyers should budget for recurring and one-time ownership costs beyond the down payment before establishing a search ceiling.
First, closing costs can include lender charges, title services, recording fees, prepaid items, and required reserves. The final amount depends on the loan structure, negotiated seller credits, title charges, and prepaid taxes or insurance. Buyers should request a written Loan Estimate early so the expected cash-to-close figure is grounded in their financing plan.
Second, property taxes can materially change affordability. California’s 1% base tax rate means the $1,769,539 planning benchmark produces approximately $17,695 per year, or about $1,475 per month, before additional voter-approved charges. Property taxes are based on assessed value, so a buyer’s actual bill may differ from an early estimate.
Third, HOA dues can be a major component of ownership costs for condos and townhomes. Fees vary by community and may cover exterior maintenance, landscaping, insurance components, amenities, reserves, or only a limited set of services. Buyers should review the monthly dues, budget, reserve funding, and governing documents before concluding that a lower list price creates a lower monthly cost.
Finally, buyers should retain funds for moving, utility setup, furnishings, initial repairs, and routine maintenance. A home can fit a lender’s approval amount while still leaving too little room for the first year of ownership.
Pro-Tip: Do not shop solely to the maximum approved loan amount; set a personal monthly ceiling that includes taxes, insurance, HOA dues, and a maintenance reserve.
What Sellers of Starter Homes in Pleasanton Expect from Buyers
Sellers of Pleasanton starter homes typically respond best to offers supported by clear financing, documented funds, and realistic transaction terms. A full pre-approval is generally stronger than an early pre-qualification because it reflects a more complete lender review of income, assets, credit, and the intended loan structure.
In a payment-sensitive market, sellers also consider whether the buyer’s terms appear credible and achievable. A buyer who has reviewed monthly costs, documented funds for closing, and coordinated with a lender can react more confidently when a suitable property becomes available. Earnest money, contingency timing, escalation language, and closing dates should match the specific listing, financing requirements, and the buyer’s risk tolerance.
The strongest offer is not automatically the highest offer. It is an offer with a credible price, workable financing, clear deadlines, and enough flexibility to reach closing without avoidable surprises. Buyers who understand their payment ceiling before writing an offer are better positioned to make decisions quickly without overcommitting.
Some Pleasanton sellers are also preparing to purchase their next home, which can influence their preferred closing dates, contingencies, and possession arrangements. Understanding these priorities can help first-time buyers prepare realistic offers while protecting their own financing and moving timelines. For additional perspective, explore our guide to coordinating a home sale and purchase in Pleasanton to understand how these overlapping transactions may affect negotiations.
Pleasanton Starter Homes vs Nearby Markets
A useful nearby-market comparison starts with the complete ownership equation rather than a headline asking price. Buyers weighing Pleasanton against another search area should compare these factors before expanding their search:
- Total projected monthly payment, including principal, interest, taxes, insurance, and HOA dues.
- Commute requirements and the practical impact of location on daily schedules.
- Property type, condition, lot size, parking, and renovation needs at the same budget.
- HOA structure, reserves, restrictions, and recurring fees for attached housing.
- The buyer’s willingness to trade preferred location or turnkey condition for more space or a lower purchase price.
Takeaway: Expanding beyond Pleasanton makes sense only when another market improves the buyer’s complete affordability-and-lifestyle equation, not simply because its asking prices appear lower.
Step-by-Step: How to Buy a Starter Home in Pleasanton in 2026
A successful Pleasanton starter-home purchase begins with a payment-first plan and moves through a disciplined offer process.
-
Get fully pre-approved. Complete lender review before serious touring, including income, assets, debts, credit, and down-payment sources. This can take several days once documents are assembled. A common problem is relying on an early estimate that excludes recurring debts or variable income.
-
Set a realistic search ceiling. Add principal, interest, property taxes, insurance, HOA dues, and a maintenance reserve to the projected monthly payment. Buyers often make the mistake of treating their maximum loan amount as a comfortable budget.
-
Choose the right property tradeoff. Decide whether a condo, townhome, smaller detached home, or property needing updates best fits the payment ceiling. This planning step should happen before broad touring begins. The common mistake is trying to preserve every preference instead of identifying the tradeoff that makes ownership workable.
-
Tour with a decision framework. Compare location, layout, condition, recurring costs, parking, storage, and future usability at each showing. Buyers often need several weeks of tours to identify consistent patterns. The risk is focusing on finishes while overlooking HOA obligations or a payment that exceeds the plan.
-
Write a complete offer. Submit a price and terms package that aligns with the pre-approval and the property’s market position. Delays or uncertainty around funds can weaken an otherwise credible offer.
-
Complete due diligence and financing. After acceptance, respond promptly to lender, escrow, and property-review requests. The timeline varies by transaction, but incomplete documentation is a common source of avoidable delay.
-
Close with a reserve. Confirm the final cash-to-close figure before signing and retain funds for move-in expenses and early repairs. Using every available dollar at closing can create unnecessary pressure during the first year of ownership.
Ready to Buy Your First Home in Pleasanton?
Finding the right starter home means balancing your budget, financing options, and long-term ownership costs. Michael Fadeeff of West Coast Luxury Real Estate helps first-time buyers compare condos, townhomes, and single-family properties while preparing for each step of the purchase.
Whether you're starting your search or preparing to make an offer, call or text (925) 399-8411 to discuss your Pleasanton homebuying goals.
Frequently Asked Questions
What is the average price of a starter home in Pleasanton?
Pleasanton does not have one uniform starter-home price because property type, condition, HOA structure, and location create wide differences within the entry-level search. Buyers often find their most attainable options among condos, townhomes, smaller detached homes, or homes that need updates.
How much do I need to earn to afford a starter home in Pleasanton?
Income needs depend on price, down payment, debts, property taxes, insurance, and HOA dues. At a 7.18% 30-year fixed rate, a $1 million loan produces principal and interest of roughly $6,790 per month before taxes, insurance, and HOA costs (Freddie Mac Primary Mortgage Market Survey, November 5, 2026).
Is Pleasanton a good place to buy a starter home right now?
Pleasanton can be a practical choice when a buyer’s payment ceiling and preferred property type match local ownership costs. The key is to evaluate the complete monthly payment and accept a clear tradeoff among property type, condition, location, or space.
What down payment assistance programs are available to first-time buyers in Pleasanton?
Eligible first-time buyers may explore CalHFA’s MyHome Assistance Program, which can provide a deferred-payment junior loan of up to 3% with a CalHFA conventional loan or up to 3.5% with a CalHFA FHA loan. The program must be paired with an eligible CalHFA first mortgage and is subject to income, occupancy, education, and lender requirements.
How long does it take to close on a starter home in Pleasanton?
A financed purchase commonly takes several weeks from accepted offer to recorded closing, though the exact timeline depends on lender processing, seller terms, title work, and document readiness. Preparing income, asset, insurance, and down-payment documentation before making an offer can help prevent avoidable delays.
Categories
Recent Posts
GET MORE INFORMATION