What matters most?
Use the explorer’s objective filters to find communities with the features you value. Save a few places with different strengths, then read their housing and everyday-life notes side by side.
The Bay Area rewards a search that looks beyond a single city name. Start with the life you want to live, compare places on their own terms, and bring the financial and property details into focus.
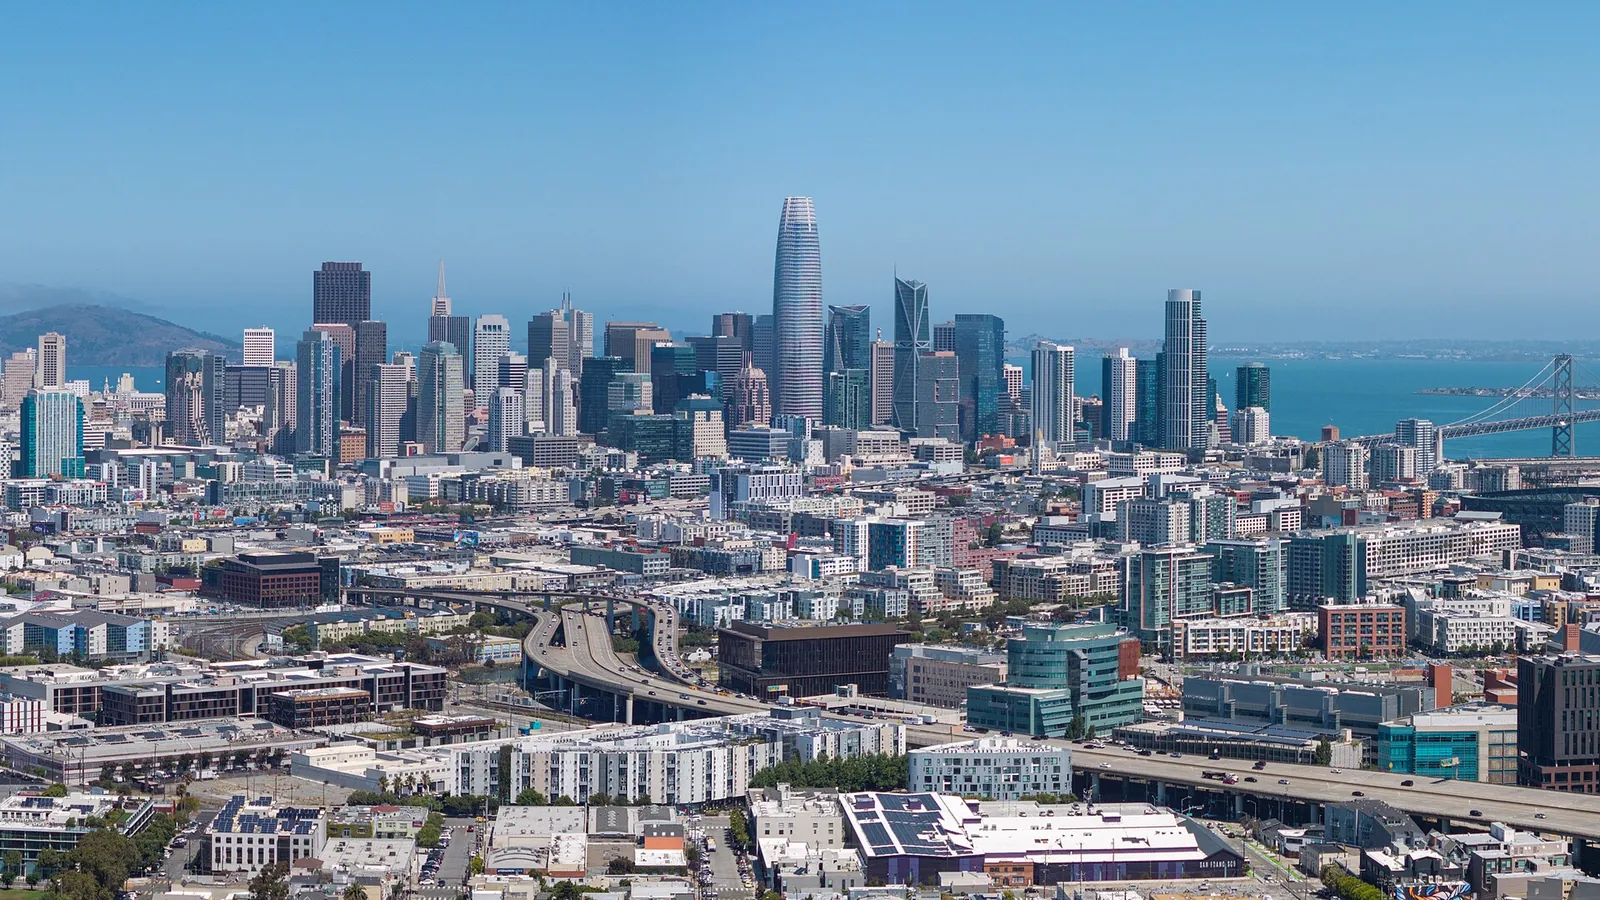
A waterfront setting, a compact downtown, and a short route to work can mean very different things from one address to another. A city guide helps you ask better questions. A real visit helps you answer them.
Use the explorer’s objective filters to find communities with the features you value. Save a few places with different strengths, then read their housing and everyday-life notes side by side.
Look at the total ownership picture: financing, property taxes, insurance, association costs, maintenance, and reserves. Obtain quotes for a real property instead of relying on a citywide assumption.
Building age, slopes, shoreline exposure, access, permits, and shared ownership all create different review questions. Match the investigation to the address and the type of home.
Choose a few communities, test your real routes, and understand which home types your budget supports. Clarify the scope and terms of representation in writing before touring with an agent.
Tour at different times when possible. Review disclosures and available records, identify additional inspections or specialist advice, and confirm lender and insurance requirements for the actual property.
Compare the price and terms with relevant evidence and your own limits. An offer needs to account for financing, due diligence, deadlines, and the consequences of each commitment.
Track inspections, financing milestones, title review, insurance, and final arrangements with the professionals involved. Confirm any wiring instructions independently using a trusted, previously verified phone number.
Explore the relationship between price and ongoing costs. These are adjustable illustrations; a lender and property-specific quotes provide the real numbers.
A share of the purchase price.
An example rate. Enter a quote from your lender.
The tax rate and insurance premium are planning assumptions. Check the property’s assessments and get an insurance quote for that address. Enter mortgage insurance if your lender requires it.
A working picture of the monthly cost.
Mortgage insurance may be required with less than 20% down. Add your lender’s estimate in “Taxes, insurance & HOA.” It is currently $0 in this total.
This is a planning estimate, not a rate quote, loan approval, or lender’s Loan Estimate. It assumes a fully amortizing fixed-rate loan. It excludes closing costs, utilities, maintenance, and any assessments or coverage you have not entered. Taxes and insurance can change.
Understand the costs with the CFPB (opens a new tab)A lender can help you understand a potential borrowing range, cash requirements, loan choices, and what documentation is needed. That gives your search useful boundaries. Prequalification or preapproval is not a final loan commitment.
Yes. Our guides can help you compare places without making a financial commitment. As your shortlist becomes a property search, align your priorities with a financing plan so you can evaluate real options.
Share the address or listing link and what you like about it. We can discuss representation, available information, and the next useful questions. Listing availability and details need to be confirmed at the time of your inquiry.
More context: CFPB homebuying resources ↗ · California DRE consumer information ↗

Tell Michael what you want more of: a walkable morning, room to grow, an easier commute, or a completely new chapter.